A lot of sole traders and landlords kept hoping Making Tax Digital would be delayed once more. It wasn’t. Since 6 April 2026, anyone with 2024-25 qualifying income above £50,000 has been in, and smaller earners are next in line. Some people will cope alone, others will want accounting services for small business owners to take the weight, and either is fine. First, though, you need to know if this is even your problem.
Does Making Tax Digital Apply to Your Business?
MTD for Income Tax targets individuals with self-employment or property income. Running a small business doesn’t automatically drag you in, which surprises people.
Is the £50,000 threshold turnover or profit?
Neither, strictly speaking. HMRC counts qualifying income, which is your gross self-employment and property income with no expenses taken off.
A joiner invoices £55,000 over the year and spends £15,000 on materials, van costs and tools. His profit is £40,000, and that’s the figure he thinks about. HMRC looks at £55,000. He’s in. Of all the mistakes on this topic, that one catches the most people.
Which income counts?
A PAYE salary stays out of the test. So does your share of partnership profit, although that still goes on your tax return.
Sole trader income and rental income are added together. A freelance designer earning £35,000, plus £20,000 from a buy-to-let, is over the line even though neither income is big on its own. Two separate sole trader businesses mean quarterly updates for each, and another one for the property.
Limited companies aren’t covered by MTD for Income Tax. Partnerships as entities aren’t either, but an individual partner with other qualifying income of their own can still be caught.
When Does MTD Apply to You?
The rollout comes in stages. Each stage looks back at an earlier tax year to decide who qualifies.
| Qualifying income | Tax year checked | MTD starts |
| Over £50,000 | 2024-25 | 6 April 2026 |
| Over £30,000 | 2025-26 | 6 April 2027 |
| Over £20,000 | 2026-27 | 6 April 2028 |
Between £30,000 and £50,000, you have until April 2027. Between £20,000 and £30,000, it’s April 2028. Below £20,000 there’s nothing to do right now, though I wouldn’t assume that lasts forever.
What Actually Changes?
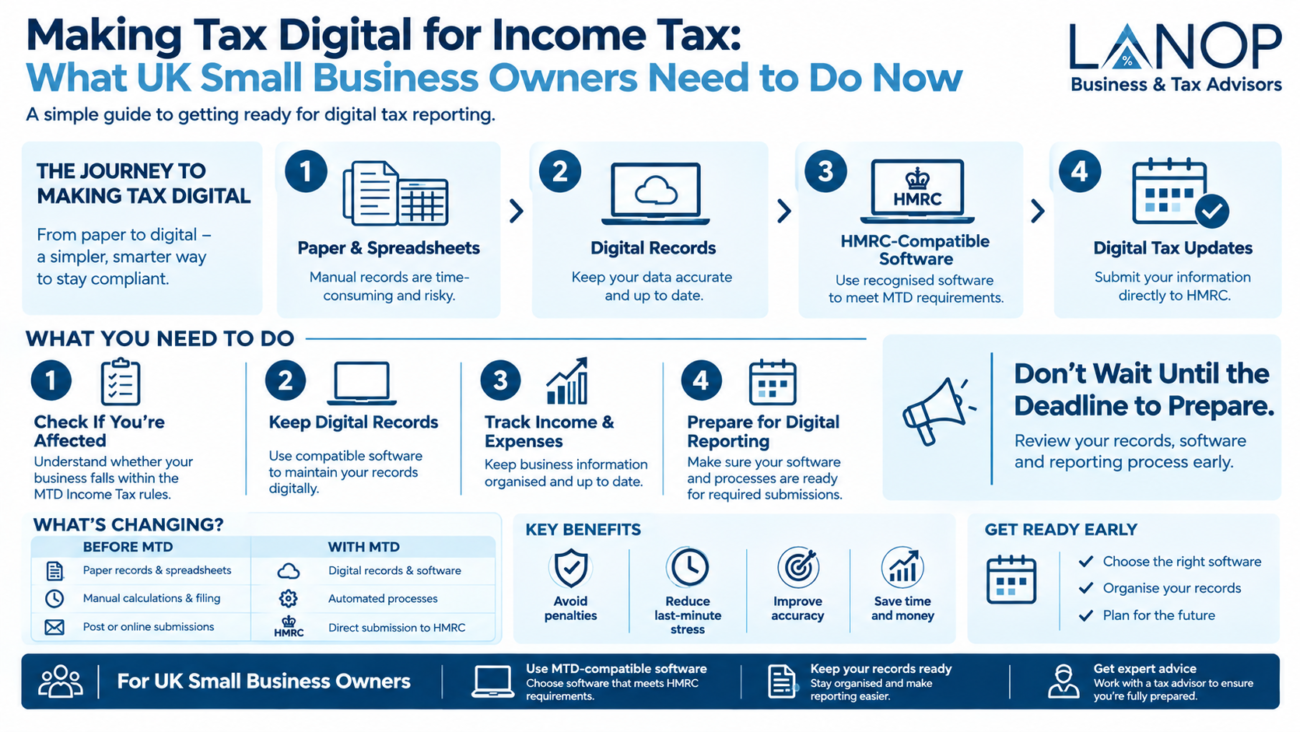
Four things happen in order: digital records, quarterly updates, year-end adjustments, then the final return.
You log income and expenses in compatible software as they happen. Four times a year, a summary goes to HMRC. When the year ends, you tidy the figures, add reliefs and allowances, file, and pay.
And no, a quarterly update isn’t a bill. You don’t pay Income Tax every three months, and your payment dates haven’t moved.
How Do You Get Ready?
Start with your qualifying income and compare it to the threshold. Then check whether an exemption, such as digital exclusion, applies to you. Once that’s settled, choose software, set up your records and sign up yourself or through an agent.
Can you still use Excel?
Yes, with one condition. The spreadsheet can stay as your record-keeping tool, but it has to connect to HMRC through bridging software, which sends the figures on your behalf. Saying MTD bans spreadsheets is a big overstatement.
Still, if reconciling yours eats an hour every month, proper accounting software will probably hand that hour back. Bank feeds and receipt capture do the dull work.
HMRC doesn’t provide software of its own, so you have to pick one. Confirm it works with MTD for Income Tax, check the bank feed quality, and make sure your accountant can log in.
Keep the paperwork as well. Digital records show HMRC what happened, and receipts and invoices prove it. Hold on to them for at least five years after the 31 January filing deadline for that tax year.
What Are the Quarterly Deadlines?
| Update period | Deadline |
| 6 April-5 July | 7 August |
| 6 April-5 October | 7 November |
| 6 April-5 January | 7 February |
| 6 April-5 April | 7 May |
Each update is cumulative. It covers everything since 6 April, not just the last quarter. You can choose calendar quarters instead, with periods running 1 April to 31 March, and you’re free to send an update early once the window is open.
What If You Miss a Deadline?
For 2026-27, HMRC has said it won’t issue penalty points for late quarterly updates. You still have to submit them. After that first year, a points-based system starts.
Late payment is a separate problem. Miss a payment date and penalties and interest can follow, no matter how tidy your updates are.
What If Your Circumstances Change?
Your business changes, and your MTD position can change with it. If income climbs past a threshold, you want to spot it early. If it falls, don’t assume you’re automatically out. Ask HMRC.
A second business or a new rental property may shift things too, so check again when either happens. Stopping trading means telling HMRC and finishing the final reporting. Switching accountant or software? Plan the handover, because digital records won’t move between agents by themselves.
Do You Need an Accountant for MTD?
Not always. The real question is whether you want to run the records, the quarterly updates and the year-end yourself.
One sole trader business and reasonably tidy books? Doing it yourself is realistic. It gets tougher with several income streams, rental property, messy expenses, or no spare time at all. A single wrong assumption about the threshold can cost more than a year of fees.
Good accounting services for small business clients cover far more than filling in forms. A small business accountant can confirm whether you’re in scope, set up your software, keep the books in order, send the quarterly updates and file your Self Assessment return. What you’re really buying is someone who catches the problem in March, before HMRC does.
Common Mistakes Worth Avoiding
Most of the trouble comes from a handful of assumptions. People treat every small business as in scope, or mix up turnover and profit. Some count PAYE or partnership income towards the threshold, and others forget rental income completely. Software gets left until the last minute, and a fair few people assume their accountant is handling everything without ever asking. Then there’s old guidance. HMRC’s rules have changed repeatedly this year, so anything written before 2026 needs a second look.
Frequently Asked Questions
Does MTD for Income Tax apply to limited companies?
No. It applies to individuals with self-employment or property income, such as sole traders and landlords. Limited companies follow separate rules. If you earn through a company and as a sole trader, only the sole trader income is tested.
Is qualifying income the same as profit?
No. Qualifying income is your gross self-employment and property income before expenses. A business earning £60,000 with £15,000 of costs makes £45,000 profit but has £60,000 qualifying income, and that higher figure decides whether you’re in scope.
Do quarterly updates mean paying tax every quarter?
No. Quarterly updates are summaries of income and expenses, not returns or bills. Your Income Tax payment dates stay exactly where they were. The updates just give HMRC a running picture of your figures through the year.
Can I keep using Excel for MTD?
Yes, but you’ll need bridging software to connect your spreadsheet to HMRC and submit the figures. The spreadsheet can still hold your records. Plenty of people switch to accounting software anyway once bank feeds and receipt capture enter the picture.
What happens if I miss a quarterly deadline this year?
For 2026-27, HMRC says it won’t apply penalty points for late quarterly updates, but you still need to submit them. A points-based penalty system applies from the following year, so build the habit now rather than later.
Conclusion
Four questions cover it: does MTD apply to you, what needs to change, which deadlines matter, and do you want to handle it alone? Start with your qualifying income figure this week, because everything else hangs off it. If the answers still feel murky,Lanop Business & Tax Advisors can review your position and provide dependable accounting services for small business owners well before your next quarterly deadline.
